Buying a Duplex or Multifamily Home to Live In Near Philadelphia
House hacking starts with the right property and financing. Learn what to review when buying a two- to four-unit home as your primary residence.
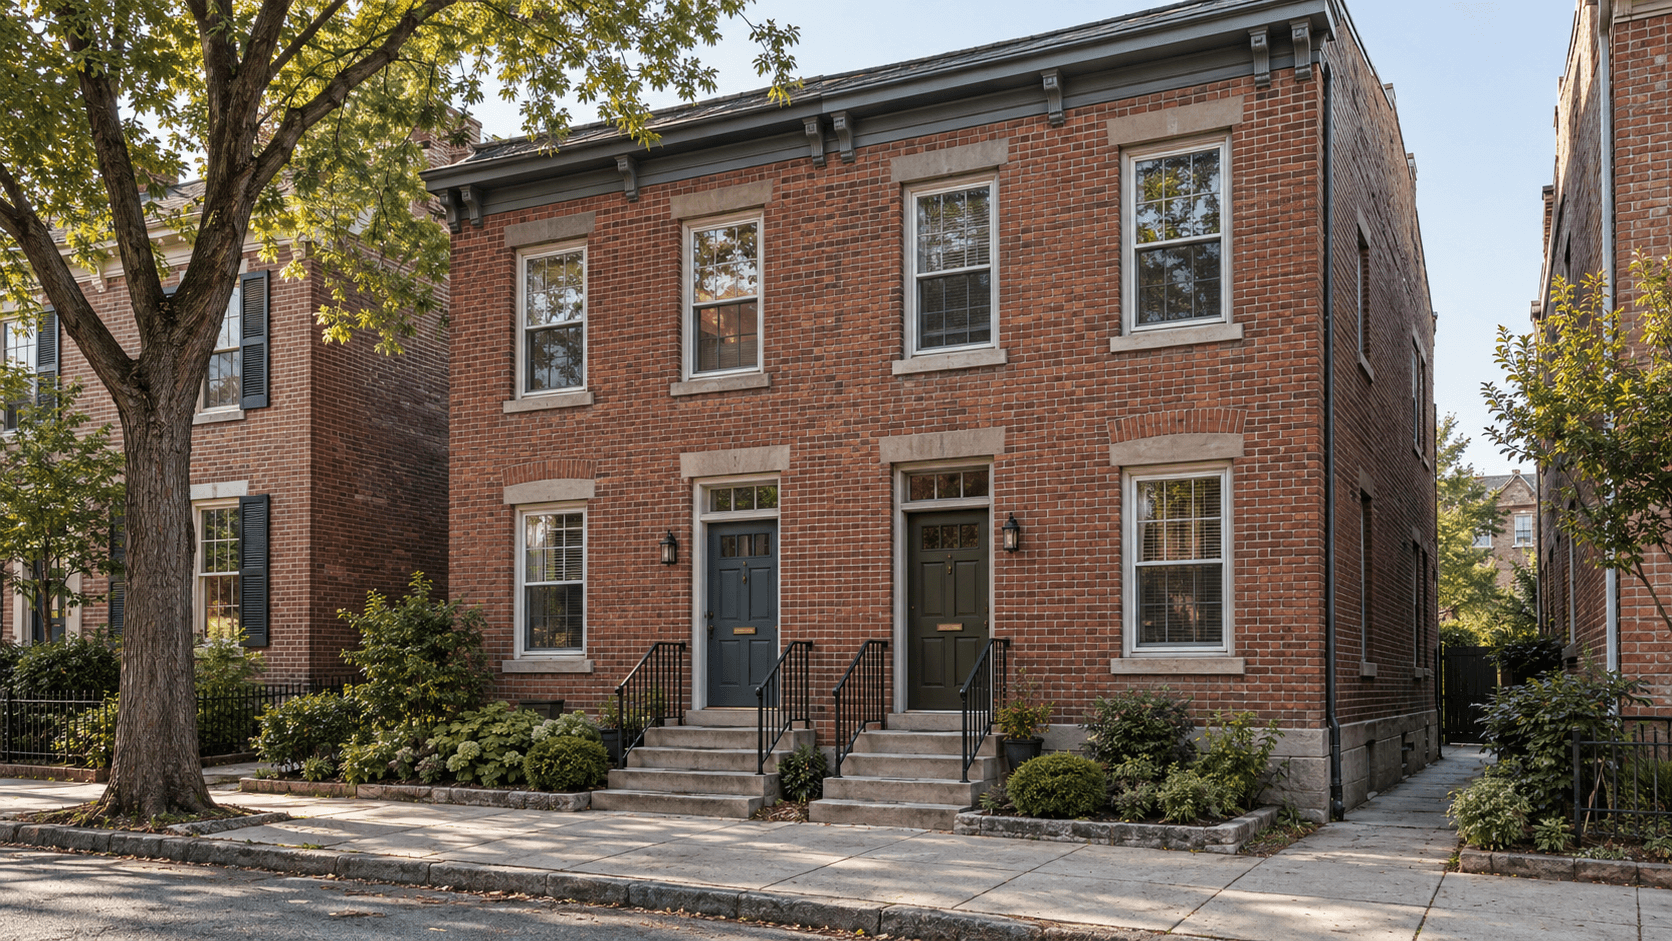
Buying a two- to four-unit property and living in one unit can combine a home purchase with rental ownership. It is often called house hacking. Your financing must reflect genuine owner occupancy and the property's legal unit count.
Barren Hill Mortgage helps buyers review owner-occupied small multifamily purchases in Philadelphia, Norristown, and surrounding Pennsylvania communities.
How is this different from buying an investment property?
An owner-occupied loan involves living in the property under the program's occupancy requirements. An investment-property loan has different qualification and pricing considerations. A business-purpose DSCR loan should not be treated as a substitute for your owner-occupied home loan.
Can the other units' rent help me qualify?
Potentially. The lender reviews eligible rent documentation and applies the selected program's calculation. You should not assume every dollar of advertised rent will count. Property management experience and other rental-income requirements may affect the result.
Check the property as carefully as the mortgage
Separate doors, meters, or kitchens do not by themselves establish legal units. Confirm the property's approved use, existing leases, occupancy, and any local rental requirements. The appraisal and lender review also evaluate the property.
An operating budget example
Hypothetical example: the other unit rents for $1,600 and the total monthly housing payment is $3,000. Subtracting rent leaves $1,400 before maintenance, vacancy, utilities, and other operating costs. That simple budget is not the lender's qualifying-income calculation.
What should you send us?
Start with the listing, legal unit information if available, leases, rent amounts, taxes, insurance estimate, and your planned occupancy. We also review your income, assets, and down payment source.
Duplex financing questions
Can a first-time buyer purchase a duplex? Potentially, subject to the selected program and borrower qualifications.
Can I count rent from the unit where I will live? Do not count hypothetical rent from your own occupied unit as tenant income.
Are five-unit properties treated the same way? No. Five or more units generally call for a different financing review from standard one- to four-unit residential programs.
Can I call a single-family home with extra kitchens a duplex? No. The legal use and lender's property classification must be established.
Review the property before relying on the rent
Send the listing and your intended living arrangement. We can help identify the financing and documentation questions before your offer.
Not Sure Which Loan Is Right for You?
Contact Barren Hill Mortgage to review your options and get pre-approved.
As featured in ForbesRocket Pro Big Pitch award winner